LLC vs Sole Proprietorship: Which Structure Fits Your Business?

Almost every week, someone sits down in my office with a business idea, a little savings, and the same opening question about llc vs sole proprietorship: “Do I need an LLC, or can I just start?” Usually they have already read four blog posts that contradicted each other. One said an LLC is essential. Another said it is a waste of money. A third said something about taxes that turned out to be wrong.
After years of forming companies, unwinding badly structured ones, and occasionally defending owners whose “protection” turned out to be thinner than they believed, I can tell you the honest answer is less dramatic than either camp suggests. This decision is not about which structure is better in the abstract. It is about which risks you are carrying, how much paperwork you are willing to live with, and where your business is going in the next three to five years.
Below is how I walk clients through this decision in practice. If you are still at the very beginning, our guide on how to start a small business covers the steps around it.
The Short Answer on LLC vs Sole Proprietorship
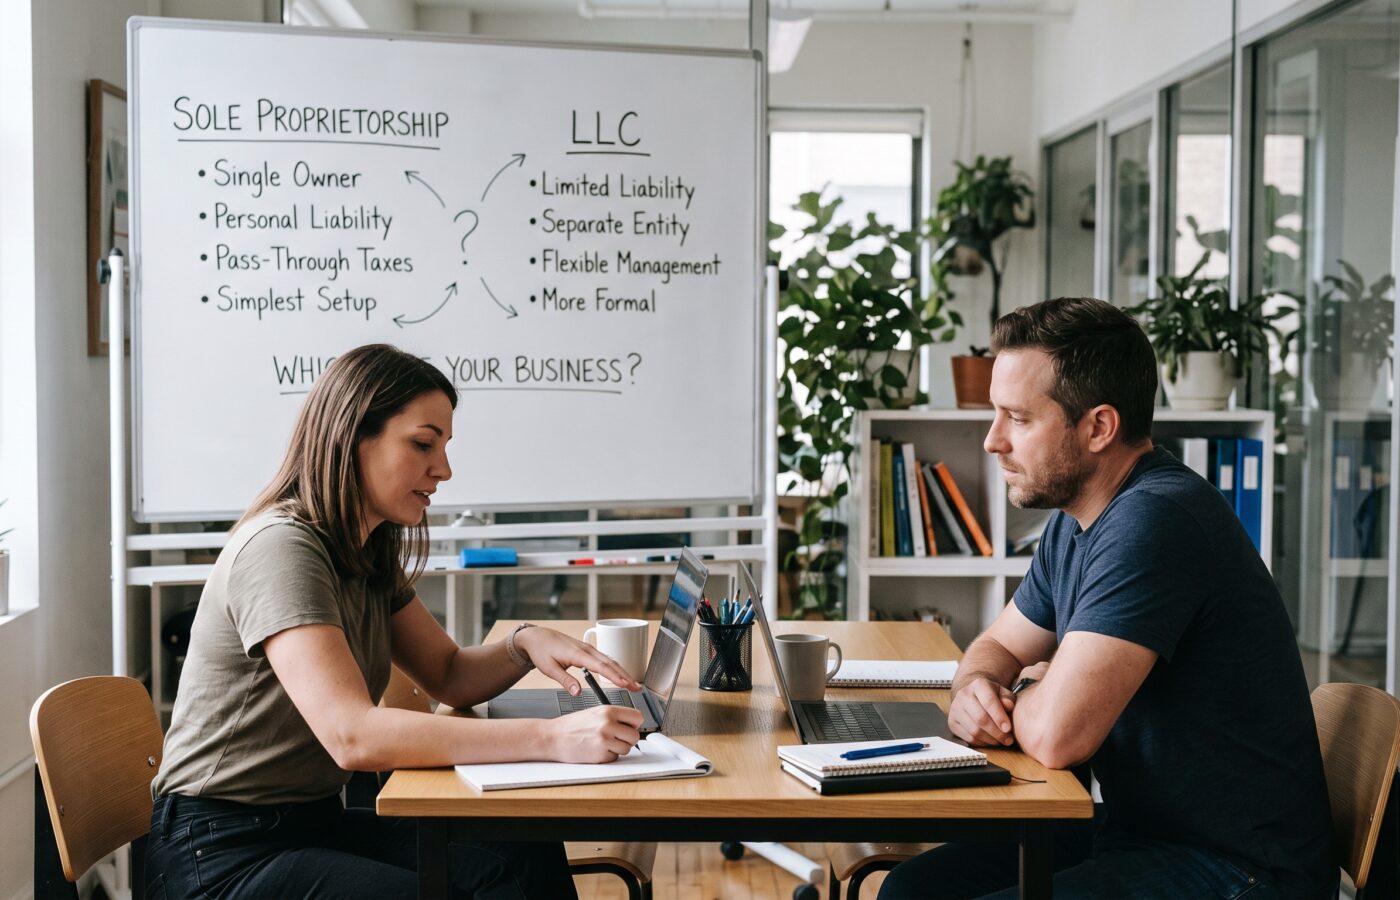
If you run a low risk business, earn modest income, have no employees, and sign very few contracts, a sole proprietorship is a perfectly respectable way to start. If you carry real exposure to lawsuits, sign leases or vendor agreements, hire people, or own assets you would hate to lose, an LLC is usually worth its cost.
Everything else in this article is the reasoning behind that sentence, and the reasoning matters, because the exceptions are where people get hurt.
What a Sole Proprietorship Really Is
A sole proprietorship is not something you form. It is something you become. The moment you start selling a product or service on your own without registering another type of entity, the law treats you as a sole proprietor. The SBA notes that you are automatically treated as one if you conduct business activity without registering as some other kind of business.
That simplicity is the entire appeal. There is no state filing to create the business, no annual report, no separate tax return. You may need a local business license, a sales tax permit, or a “doing business as” registration if you operate under a name other than your own, but that is typically the extent of it.
The catch is built into the definition. A sole proprietorship does not create a separate legal entity. You and the business are the same person. Your business bank account, if you have one, is really just your personal account with a different label. Your business debts are your debts. A judgment against the business is a judgment against you.
Clients sometimes push back on this. “But I have a business name and a separate checking account.” That does not matter. Legally, nothing stands between the business and your house, your car, your savings, or your future wages.
What an LLC Really Is
A limited liability company is a creature of state law. You create one by filing formation documents, usually called articles of organization or a certificate of formation, with the secretary of state where you are organizing. From that point forward, the LLC exists as its own legal person. It can own property, enter contracts, open bank accounts, and be sued in its own name.
The owners are called members. An LLC can have one member or many. When people compare an LLC to a sole proprietorship, they are almost always talking about a single member LLC, because that is the structure a solo owner would actually choose.
The central promise of an LLC is that the company’s debts and liabilities belong to the company, not to you. If the business fails owing money to a supplier, the supplier generally has a claim against the LLC’s assets, not your personal ones. That separation is the whole reason the structure exists, and it sits at the heart of every llc vs sole proprietorship conversation I have with clients.
Liability: Where the LLC vs Sole Proprietorship Difference Really Lives
This is the part of the comparison that deserves the most attention, and also the part most often oversold.
What an LLC Protects You From
An LLC shields you from the ordinary obligations of the business. Think unpaid invoices to vendors, a commercial lease the company signed, a breach of contract claim brought against the company, or a slip and fall at a business location where the claim is against the business as the operator. If the company cannot pay, the creditor’s recovery is generally limited to what the company owns.
It also shields you, in most situations, from liability for the acts of employees. If your delivery driver causes an accident while working, the claim runs against the business. As a sole proprietor, that claim runs straight to you.
What an LLC Does Not Protect You From
Here is what I wish every new business owner understood before filing anything.
Your own negligence. If you personally cause harm, you are personally liable, LLC or not. A contractor who installs a faulty railing, an accountant who botches a return, a massage therapist who injures a client: the LLC does not stand between them and their own conduct. This is especially important for licensed professionals.
Personal guarantees. Banks, landlords, and equipment lessors know exactly how an LLC works, which is why they ask new business owners to personally guarantee loans and leases. Once you sign that guarantee, the LLC’s protection for that debt is gone, by your own agreement. Nolo explains that when you personally guarantee a company obligation, the creditor can pursue your personal assets if the business defaults.
Unpaid payroll taxes. The IRS can hold “responsible persons” personally liable for withheld employment taxes that never reached the government. An LLC will not save you there.
Fraud and misconduct. Courts will not let you hide wrongdoing behind an entity.
So the protection is real, but it is narrower than the marketing suggests. What it does well is separate you from the business’s contractual and operational liabilities. For many owners, that alone justifies the structure.
LLC vs Sole Proprietorship Taxes: Less Different Than You Think
Here is where I spend a lot of time correcting misinformation. Many people believe forming an LLC will lower their taxes automatically. It will not, at least not by default.
Default Tax Treatment Is Nearly Identical
The IRS does not have a separate tax category for LLCs. Instead, it slots them into existing ones. According to the IRS, a single member LLC that does not elect corporate treatment is a “disregarded entity,” and its activity is reported on the owner’s own federal return.
In plain terms, a single member LLC with default treatment is taxed exactly like a sole proprietorship. You report income and expenses on Schedule C, you pay ordinary income tax at your individual rates, and you pay self employment tax on your net earnings using Schedule SE. Profit flows through to you whether or not you take it out of the business.
Self employment tax is the piece that stings. It covers both halves of Social Security and Medicare, for a combined rate of 15.3 percent on net earnings up to the annual Social Security wage base, with the Medicare portion continuing above that. Sole proprietors and default LLC owners pay it the same way.
Both structures are also generally eligible for the qualified business income deduction under Section 199A, subject to income thresholds and limits for certain service businesses. Structure alone does not change your eligibility there.
Where the LLC Opens a Door
The real tax difference is optionality. An LLC can elect to be taxed as a corporation, and most commonly, as an S corporation. A sole proprietorship cannot make that election at all. You would have to form an entity first.
Under an S corporation election, you become an employee of your own company. You pay yourself a reasonable salary, which is subject to payroll taxes, and you can take the remaining profit as distributions that are not subject to self employment tax. For an owner netting a healthy profit, the savings can be meaningful.
I want to be careful here, because I have watched this strategy backfire. The salary must genuinely be reasonable for the work you perform, and the IRS does scrutinize owners who pay themselves almost nothing. You will also take on payroll processing, a separate business tax return, and higher accounting fees. For an owner netting modest profits, those costs often eat most or all of the savings. I generally tell clients not to consider the election until their net profit is comfortably beyond what a reasonable salary would be for their role, and to run the actual numbers with a CPA before filing Form 2553.
The takeaway: an LLC does not lower your taxes today. It gives you a flexible vehicle that can lower them later.
Cost and Paperwork: LLC vs Sole Proprietorship
A sole proprietorship costs close to nothing to start. An LLC costs something, and that cost recurs.
Formation Costs
State filing fees for LLC formation vary widely, often somewhere between about $50 and $500. Some states also require you to publish a notice of formation in local newspapers, which can add real money in certain counties.
Ongoing Costs
This is the part people forget. Most states require an annual or biennial report with a fee. Some impose a minimum annual tax regardless of profit. California is the classic example: LLCs there generally owe an $800 minimum annual franchise tax even in a year the business loses money. Before you form, look up your own state’s annual obligations and add them to your budget for every year you expect to operate.
You will also need a registered agent, meaning a person or service with a physical address in the state who accepts legal papers on the company’s behalf. You can often serve as your own, but many owners prefer a service for privacy, which costs money each year.
The Operating Agreement
Every LLC should have a written operating agreement, even a single member one. Some states do not strictly require it, and I still insist on it. The agreement documents that the company is a real, separate entity with its own rules. It governs what happens if you become incapacitated or die, which matters enormously to your family. And it is one of the first documents a court will look at if someone ever argues your LLC is a sham.
Banking, Contracts, and Credibility
There are practical, everyday differences in the llc vs sole proprietorship choice that do not show up in tax tables.
Banking. Most banks require formation documents and an EIN to open a business account for an LLC. That friction is actually healthy, because it forces the separation of money that protects you.
Contracts. Larger clients and corporate vendors often prefer, and sometimes require, contracting with an entity rather than an individual. Their procurement teams want a company name, an EIN, and a certificate of insurance.
Credibility. I will not overstate this. Customers rarely check your entity type. But “Riverside Design LLC” on an invoice does signal permanence in a way that an individual’s name sometimes does not, particularly in business to business work.
Growth and ownership. If you plan to bring in a partner, an investor, or a key employee with equity, an LLC gives you a framework to do it. A sole proprietorship, by definition, cannot have a second owner. The moment someone else shares profits and control with you, you may have unintentionally formed a general partnership, which carries its own unlimited liability problems.
Keeping the Shield Intact
An LLC is not a magic certificate. It is a promise you have to keep. When owners treat the company as an extension of their personal wallet, courts can disregard the entity entirely. Lawyers call this piercing the veil.
The factors courts commonly weigh include ignoring formalities, mixing personal and company funds or diverting company assets for personal use, inadequate capitalization, and manipulation of the company’s assets and liabilities. Nolo also observes that smaller businesses tend to be more exposed to veil piercing, often because owners use company assets for personal purposes.
Single member LLCs are, frankly, the easiest to pierce, because there is no partner watching the books and no one to complain when the owner pays the mortgage from the business account. Here is the routine I give every client:
- Open a dedicated business bank account and run every business dollar through it.
- Never pay personal bills from the company account. If you need money, take a documented owner draw.
- Sign contracts in the company’s name, with your title, so it is clear the LLC is the party.
- Keep the company adequately funded for its realistic obligations.
- File your annual reports on time. A company administratively dissolved for missed filings may leave you exposed.
- Keep a simple record of major decisions, even when you are the only member.
None of this is burdensome once it becomes habit. Skipping it is how a $500 filing becomes worthless at the exact moment you need it.
The Overlooked Third Option: Insurance
When clients ask me whether an LLC will “protect them,” I often answer with another question: “What insurance do you carry?” In my experience, insurance belongs in every llc vs sole proprietorship discussion, yet it is the piece most owners leave out.
General liability coverage, professional liability coverage, commercial auto coverage, and an umbrella policy frequently do more practical work than entity choice. Insurance pays for a defense lawyer. It pays the settlement. An LLC only limits what a creditor can collect after a judgment.
For the risks an LLC does not cover at all, like your own professional negligence, insurance is the only real protection you have. The best answer for most owners is not “LLC or insurance.” It is both, sized to the business.
When a Sole Proprietorship Makes Sense
I recommend clients stay sole proprietors more often than people expect. It tends to be the right call when:
- You are testing an idea and are not yet sure it will become a real business.
- The work carries very little liability risk, such as freelance writing, tutoring, or certain online consulting.
- There are no employees, and you do not plan to hire soon.
- You will not sign significant leases, loans, or long vendor contracts.
- Your personal assets are modest, so there is less to protect.
- Annual LLC costs in your state are heavy relative to your expected profit.
The SBA itself describes the sole proprietorship as a reasonable choice for low risk businesses and for owners who want to test an idea before committing to a more formal structure. I agree. Starting simple is not a mistake, provided you revisit the decision as the business grows.
When an LLC Is the Better Call
The balance shifts toward an LLC when:
- You work on clients’ property, handle their goods, or provide physical services where injuries and damage happen.
- Employees or contractors act on your behalf, or you are about to hire them.
- A commercial lease, equipment financing, or contracts with real dollar exposure are on the table.
- You own a home, retirement savings, or other assets worth protecting.
- A partner or investor is likely to join.
- Your profit is climbing to the point where an S corporation election could make sense.
- Clients or vendors require you to contract as an entity.
If two or three of those describe you, the annual cost of an LLC is usually a bargain compared to the exposure it addresses.
Switching From a Sole Proprietorship to an LLC Later
Many owners start as sole proprietors and convert once the business proves itself. That is a sound strategy, but it is not a single click. Converting typically means forming the LLC, obtaining a new EIN in most cases, opening new bank accounts, transferring assets and contracts into the company, updating licenses and permits, and notifying clients and vendors. Some contracts cannot be assigned without the other party’s consent.
Also understand that forming an LLC later does not retroactively protect you from liabilities that arose while you operated as a sole proprietor. If a claim stems from work you did last year as an individual, the new LLC will not absorb it.
The lesson: if you already know you will need an LLC within a year, it is usually cheaper and cleaner to start with one.
A Practical LLC vs Sole Proprietorship Framework I Use With Clients
When someone asks me to help them decide, I work through five questions:
- What is the worst realistic claim this business could face? If the honest answer could exceed your savings, take liability seriously.
- What will you sign? Leases, loans, and large contracts push toward an LLC.
- Who will act on your behalf? Employees and subcontractors increase exposure.
- What does your state charge each year? Weigh that number against your expected profit.
- Where do you want to be in three years? Partners, investors, and higher profits all favor the flexibility of an LLC. Putting that answer into a business plan makes the decision much clearer.
There is no formula that spits out the answer, but these questions consistently get clients to a decision they feel good about, rather than one they made because a website told them to.
FAQ: LLC vs Sole Proprietorship
Is a single member LLC the same as a sole proprietorship?
For federal income tax purposes, by default, they are treated almost identically, since the IRS disregards the single member LLC and its income is reported on the owner’s return. Legally, they are very different, because the LLC is a separate entity that can shield you from business debts. See the IRS guidance on single member LLCs.
Does an LLC save me money on taxes compared to a sole proprietorship?
Not automatically. Default LLC taxation mirrors a sole proprietorship. Savings typically come only if you later elect S corporation status and your profit is high enough to justify the added payroll and accounting costs. A CPA should run the numbers first.
Can I be sued personally if I have an LLC?
Yes, in several situations: for your own negligence, for debts you personally guaranteed, for unpaid payroll taxes, and when a court pierces the veil because the company was not run as a separate entity. Nolo’s overview of piercing the corporate veil explains the risk well.
Do I need a lawyer to form an LLC?
Not strictly. Many owners file online through their secretary of state. I do recommend professional help with the operating agreement and with any decision involving partners, licensed professions, or significant assets.
Can I change from a sole proprietorship to an LLC later?
Yes. You form the LLC and move the business into it. Expect new bank accounts, likely a new EIN, updated licenses, and contract assignments. The SBA’s guide to choosing a business structure notes that conversion rules can vary by location.
What is the cheapest way to start a business?
A sole proprietorship, since there is usually no state formation fee. Cheapest at the start is not always cheapest overall, though, if a single uninsured claim lands on your personal assets.
Final Thoughts on LLC vs Sole Proprietorship
This is one of the first legal choices you make as a business owner, and it is also one of the easiest to revisit. Start with a clear look at your risks, your contracts, and your growth plans. If the business is small, quiet, and low risk, a sole proprietorship with good insurance may be all you need for now. If you are signing real obligations, hiring people, or building something with lasting value, an LLC is a modest annual cost for a meaningful layer of separation.
Whatever you choose, run it properly. The structure only works as well as the habits behind it. And because entity rules, fees, and tax treatment vary from state to state, a short consultation with a business attorney and a CPA who know your jurisdiction is money well spent before you file anything.
References
- U.S. Small Business Administration. Choose a Business Structure
- Internal Revenue Service. Single Member Limited Liability Companies
- Nolo. Personal Liability and Piercing the Corporate Veil
- Nolo. When Are You Personally Liable for LLC or Corporate Debt?
- Orrick Tech Studio. What Is Piercing the Corporate Veil?
- Shopify Blog. Small business structure comparison.
- Salesforce Blog. Small business structure guide.
- UpCounsel. Business entity comparison guide.