The 50/30/20 Budget Rule Explained (With Examples)
The 50/30/20 rule is usually the first budgeting framework I bring up with a new client. However, it’s rarely the one they end up following to the letter. That isn’t a knock on it. In fact, after years of sitting across the table from people with bank statements spread out and a shoebox of receipts nearby, I’ve come to see the rule as a diagnostic tool. In other words, it tells you, in about ten minutes, where your money is out of balance. What you do with that information, of course, is the actual work.
In this guide, I’ll walk through what the rule says, where it came from, and how to calculate it correctly, since most people get one step wrong. I’ll also show how it plays out for real households. Finally, I’ll tell you when I advise clients to bend it, and when I tell them to put it down and try something else.
What the 50/30/20 Rule Actually Says
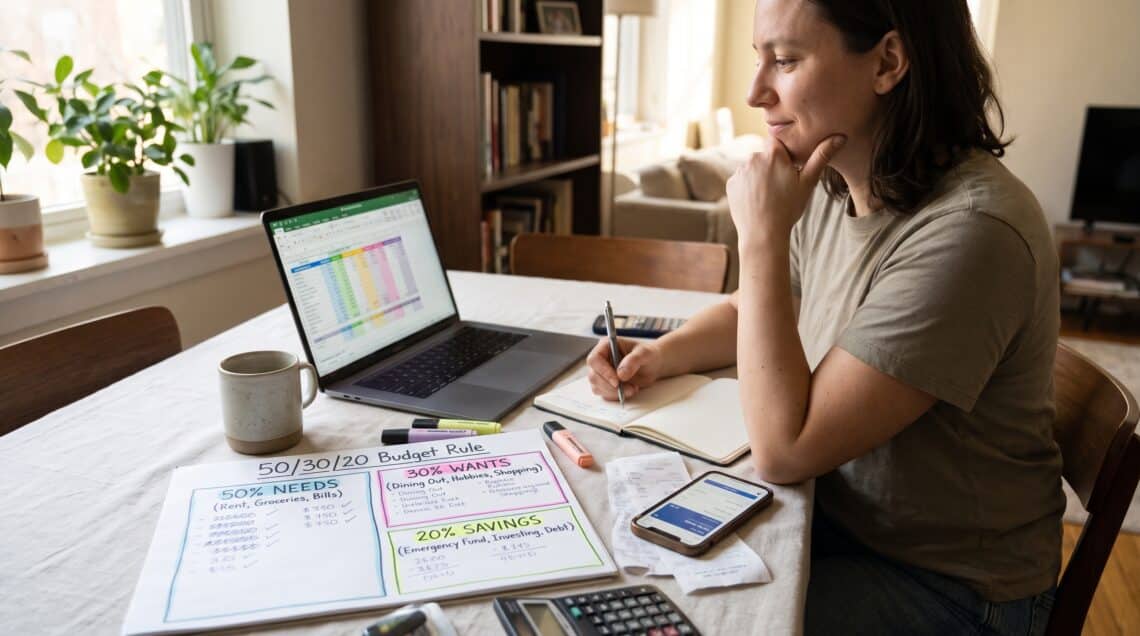
The rule divides your take home pay into three buckets:
- 50% for needs. These are the bills you must pay to keep a roof overhead, food on the table, the lights on, and yourself able to get to work.
- 30% for wants. This covers everything that makes life enjoyable but isn’t strictly required.
- 20% for savings and debt repayment. This is money for your future self, whether that’s an emergency fund, retirement, or paying down balances faster than the minimum.
That’s the whole system. In short, there are no dozens of categories and no tracking of every coffee. Instead, you work with three numbers.
Where the 50/30/20 Rule Came From
Elizabeth Warren and her daughter, Amelia Warren Tyagi, popularized the framework in their 2005 book All Your Worth: The Ultimate Lifetime Money Plan. At the time, Warren was a bankruptcy law professor, and the book grew out of her research into why middle class families were going broke. Her conclusion was that families usually weren’t sunk by lattes and vacations. Instead, they were sunk by fixed costs, such as the mortgage, the car payments, and the insurance, which had quietly grown too large to absorb any surprise. As a result, the 50% cap on needs was designed as a guardrail against exactly that.
I mention the origin because it changes how you should read the rule. Specifically, the most important number in 50/30/20 isn’t the 20. It’s the 50. In other words, savings is the goal, but needs are the pressure point.
Step One: Get the Right Starting Number for the 50/30/20 Rule
This is where I see the most mistakes. First of all, the rule is built on after tax income, which means the money that actually lands in your account. So it’s not your salary, and it’s not your gross pay.
Add Back Your Payroll Deductions
There is a wrinkle, however. If money is taken out of your paycheck before it reaches you, such as a 401(k) contribution or health insurance premiums, you need to add those back to get an honest picture.
For example, say your gross pay is $5,500 a month. After taxes, you’d have $4,400. Meanwhile, your employer also withholds $275 for your 401(k) and $180 for health insurance, so your deposit is $3,945.
If you build your budget from $3,945, your retirement contribution disappears from the math, and therefore your savings rate looks worse than it is. Similarly, your health premium disappears, so your needs look smaller than they are.
The fix is simple:
- First, start with your net deposit ($3,945).
- Next, add back retirement contributions ($275), because these count toward your 20%.
- Then, add back health premiums ($180), since these count toward your 50%.
As a result, your true after tax income is $4,400. That’s the number you split. For anyone paid irregularly, or paid biweekly (which means 26 checks a year, so two months each year have three paychecks), I’ll cover that in the examples below.
Step Two: Sort Your Spending Under the 50/30/20 Rule
Next, here’s how the three buckets break down in practice.
Needs (50%)
Needs are expenses that, if you stopped paying them, would create a real problem with your housing, health, safety, job, or legal standing. In my sessions, these usually include:
- Rent or mortgage, plus property taxes and homeowners or renters insurance
- Utilities such as electricity, water, gas, and a basic phone plan
- Groceries, but not restaurants
- Transportation to work, including car payment, gas, insurance, or transit fare
- Health insurance premiums, copays, and necessary prescriptions
- Childcare that you need in order to work
- Minimum payments on all debts
That last one surprises people. However, Warren’s framework treats the minimum required payment on a credit card or loan as a need, because missing it damages your credit and can trigger penalties. On the other hand, anything you pay above the minimum moves to the savings bucket.
Wants (30%)
Wants, by contrast, are the choices. For instance, these include dining out, streaming services, travel, hobbies, gym memberships, new clothes beyond the basics, the upgraded phone plan, and concert tickets.
The gray areas are where honesty matters most. For example, your grocery bill is a need. Still, the portion of that bill that goes toward specialty snacks and premium coffee beans is, strictly speaking, a want. Likewise, a car is a need for most people outside major cities. Even so, the difference between a reliable $350 car payment and a $780 one is a want wearing a need’s clothing.
I don’t ask clients to split every receipt this way. Instead, I ask them to notice it. So when someone tells me their needs are eating 68% of their income, the first thing we do together is look for wants hiding inside the needs column.
Savings and Debt Repayment (20%)
Finally, this bucket covers:
- Emergency fund contributions
- Retirement contributions, including what’s withheld from your paycheck
- Extra payments on credit cards, student loans, or other debt beyond the minimum
- Saving for big goals, such as a down payment or a future car paid in cash
Example One: A Single Professional Who Fits the 50/30/20 Rule
To begin, let’s look at the clean version so you can see the math.
Jordan is 29, single, and brings home $4,200 a month after taxes and add backs. Under the 50/30/20 rule, that means:
- Needs: $2,100
- Wants: $1,260
- Savings and debt: $840
Here’s what Jordan’s actual month looked like when we mapped it:
Needs: $2,060
Rent with a roommate: $1,150. Utilities and phone: $190. Groceries: $380. Car insurance and gas: $240. Student loan minimum: $100.
Wants: $1,300
Restaurants and takeout: $420. Subscriptions: $65. Gym: $45. Travel fund: $250. Shopping and everything else: $520.
Savings: $840
Roth IRA: $400. Emergency fund: $240. Extra student loan payment: $200.
As you can see, Jordan is almost exactly on target, and that’s the point of this example. When the rule fits, it fits easily. In that case, the main benefit is permission. Because the future is already funded, Jordan can spend $1,300 a month on enjoyment without guilt.
Example Two: A Couple Squeezed by Housing Under the 50/30/20 Rule
However, most of the people I counsel don’t look like Jordan. Instead, they look more like this.
Marcus and Lena bring home a combined $7,800 a month. Under the rule, their targets would be:
- Needs: $3,900
- Wants: $2,340
- Savings: $1,560
Their actual needs, on the other hand, looked like this:
- Rent: $2,450
- Two car payments plus insurance: $820
- Groceries: $900
- Utilities: $310
- Health premiums: $280
- Credit card minimums: $240
Altogether, that’s $5,000, or about 64% of take home pay. As a result, it left only $2,800 for wants and savings combined. They were spending roughly $2,600 of that on wants and saving about $200 a month. Consequently, they couldn’t understand why they felt broke on what looks like a solid income.
Why This Is So Common
In fact, they are far from alone. According to the Bureau of Labor Statistics, the average American household spent about $2,189 a month on housing in 2024, which was a third of all household spending. Moreover, housing and transportation together took up more than half. Similarly, Harvard’s Joint Center for Housing Studies reported that 22.7 million renter households, nearly half of all renters, spent more than 30% of their income on housing that year. For a look at where these costs are heading, see our cost of living trends for 2027.
What We Changed
So what did we do? First, we didn’t try to force them into 50%, because that would have meant moving, and they had a lease and a kid in a school they loved. Instead, we set a 60/20/20 target for the next year and built a two step plan:
- Cut wants to $1,560, or 20%. It wasn’t painless, but they found most of it in takeout and two subscriptions they’d forgotten about.
- Attack the fixed costs over time. For example, when one car loan was paid off eight months later, they redirected that $390 straight to savings instead of absorbing it. Then, at lease renewal, they negotiated a modest increase rather than accepting the first offer.
A year later, they were at 58/20/22. Admittedly, that’s not textbook, but it’s much better. This is exactly what I mean when I say the rule is a diagnostic. It showed Marcus and Lena that their problem wasn’t discipline. Rather, it was fixed costs, and that changed where they put their energy.
Example Three: Using the 50/30/20 Rule to Pay Off High Interest Debt
Priya brings home $3,600 a month and carries $6,000 on a credit card at 24% APR. Therefore, her 20% bucket is $720.
Save First or Pay Debt First?
The question I hear constantly is whether to save or pay down debt. My answer is usually both, but in a specific order:
- First, build a small starter emergency fund. Otherwise, the next flat tire goes right back on the card. So we set Priya’s target at $1,000.
- Then, send everything else at the highest interest debt.
For the first few months, her 20% was split like this:
- Emergency fund: $200
- Extra credit card payment: $520, on top of her minimum, which stays in the needs column
What Happened Next
Once the starter fund reached $1,000 after five months, the full $720 went toward the card. As a result, that $6,000 balance was gone in a little over a year. In addition, she saved well over a thousand dollars in interest compared with paying minimums only.
Then the real magic happened. The money she’d been sending to the card didn’t vanish into wants. Instead, it rolled straight into her retirement account. In my experience, that habit of redirecting freed up money is more valuable than any single percentage.
Example Four: The 50/30/20 Rule With Variable Income
Freelancers, gig workers, commissioned salespeople, and seasonal workers often tell me the 50/30/20 rule doesn’t work for them. Actually, it can, with one adjustment.
Theo is a self employed designer. Over the past twelve months, his take home pay, after setting aside money for quarterly estimated taxes, ranged from $3,000 in his slowest month to $7,200 in his best. On average, that came to about $4,800.
Budget From Your Lowest Month
The mistake is budgeting off the average, because average months don’t pay the rent in slow months. Instead, we did this:
- First, build the needs budget from the lowest month. In other words, Theo’s needs had to fit inside $3,000, ideally well under it. As it turned out, they came in at $2,450.
- Next, pay yourself a fixed “salary.” Theo moves $4,000 from a separate business account into his personal account every month.
- Finally, let strong months build a buffer. Extra income stays in the business account until it holds three months of his salary. After that, anything above it gets split evenly between savings and wants.
On his $4,000 salary, Theo’s split looked like 61/19/20 in practice. Granted, that’s not a perfect fit, but it’s stable. And above all, stable is what variable earners need most.
Example Five: The 50/30/20 Rule for Higher Income Households
On the other hand, the rule gets easier, and sometimes less useful, as income rises. For instance, a household bringing home $15,000 a month might have needs of only $5,500, which is about 37%. So should they spend 43% on wants because the rule leaves room for it?
I’d argue no. At higher incomes, the 20% savings target is a floor, not a ceiling. For example, someone who started saving late, wants to retire early, or has kids heading to college soon should probably flip it and aim for something like 40/20/40. After all, the rule is calibrated for the middle of the income spectrum, which is exactly where Warren’s research was focused.
When to Adjust the 50/30/20 Rule Percentages
Over the years, a handful of variations have come up regularly in my practice:
- 60/20/20 works well for high cost housing markets, early career earners, or households with young children in daycare.
- 70/20/10 serves as a temporary survival budget when income has dropped or costs have spiked, so the goal is simply to stop the bleeding.
- 50/20/30, or something similar, suits people with aggressive goals, such as paying off debt fast or catching up on retirement.
- 80/20, where you save 20% first and don’t track the rest, fits people who find categorizing exhausting but already have their fixed costs under control.
As a rule of thumb, you can move the needs and wants numbers around. However, think hard before you drop savings below 10%. After all, the Federal Reserve’s most recent survey on household finances found that 63% of adults would cover a $400 emergency with cash or its equivalent. In addition, only about 55% had enough set aside to cover three months of expenses. Consequently, a thin savings bucket leaves you one surprise away from new debt.
Common 50/30/20 Rule Mistakes I See
Using gross income. This makes every number unrealistic and, as a result, almost guarantees failure in month one.
Counting debt payments twice. Remember, minimums go in needs, while extra payments go in savings. So never count them in both.
Treating the wants bucket as optional. People who budget 0% for fun usually rebound with a spending binge. Therefore, a defined amount for enjoyment is part of what makes a budget sustainable.
Expecting perfection in month one. Instead, think of the first month as data and the second month as adjustment. Typically, real change shows up by month three.
Ignoring irregular expenses. Car registration, annual subscriptions, holiday gifts, and the dentist all happen every year. So divide the yearly total by twelve and set it aside monthly. Otherwise, those expenses will blow up a perfectly good budget.
How to Set Up Your Own 50/30/20 Rule Budget This Week
If you want to try this, here’s the process I walk clients through:
- First, calculate your true after tax income, adding back retirement and health deductions.
- Next, pull the last two or three months of bank and card statements. Don’t guess, because memory is generous while statements are honest.
- Then, tag each expense as a need, a want, or savings.
- After that, total each bucket and divide by your income to get your actual percentages.
- Now compare your results to 50/30/20, and notice where you’re over and by how much.
- Pick one lever, not five. For example, if needs are the issue, focus on the biggest fixed cost. Likewise, if wants are the issue, pick the category that surprised you most.
- Automate the 20% by setting transfers to move savings out on payday, before you see it. In my experience, this is the single most effective habit there is.
- Finally, check in monthly for three months, and then quarterly once it’s stable.
In addition, the Consumer Financial Protection Bureau’s free Your Money, Your Goals toolkit includes spending trackers and cash flow budget worksheets that work well for steps two through five. In fact, it’s the same material many counselors use with clients.
Is the 50/30/20 Rule Right for You?
Generally, the rule works best if you have a steady paycheck, your fixed costs are reasonable for your income, and you want structure without micromanaging every dollar. It’s also a good fit for people who’ve never budgeted and feel overwhelmed by detailed systems.
On the other hand, it works less well if you’re in a crisis, such as being behind on rent or facing collections. Similarly, it struggles when your income is very low relative to local costs, or when you need tighter control because of a specific problem like compulsive spending. In those situations, I usually recommend a zero based budget, where every dollar gets an assignment. Alternatively, a short term cash flow plan that pays the most urgent bills first can help.
Still, for most people, most of the time, 50/30/20 is the right first step. Ultimately, it’s simple enough to start today and honest enough to show you what’s really going on.
Frequently Asked Questions About the 50/30/20 Rule
Is the 50/30/20 rule based on gross or net income?
It’s based on after tax income. However, you should add back any retirement contributions and health premiums withheld from your check so those count in the right buckets. For a helpful walkthrough, see Acorns.
Who created the 50/30/20 rule?
Elizabeth Warren and Amelia Warren Tyagi popularized it in their 2005 book All Your Worth. In addition, Fox Business covers its background and how to apply it.
Do debt payments count as needs or savings?
Both, depending on the type. Minimum required payments are needs, while anything extra goes into the 20% bucket. Furthermore, Bankrate explains why paying down debt faster saves on interest.
What if my needs are more than 50% of my income?
That’s common, especially for renters in expensive areas. So try a 60/20/20 split temporarily, and meanwhile work on lowering your largest fixed cost. For more on this variation, see CollegeAve.
Does the 50/30/20 rule work with irregular income?
Yes, as long as you build your needs budget around your lowest earning month and pay yourself a steady amount from a buffer account. Also, Kiplinger covers who the rule suits best.
How should I split the 20% savings bucket?
A common approach is half toward an emergency fund and half toward retirement. Then, once you have three to six months of expenses saved, shift the emergency share to other goals. For example, Citizens Bank offers one version of that split.
Is the 50/30/20 rule good for beginners?
Absolutely, because it uses just three categories. In fact, SoFi outlines its main benefits for new budgeters.
References
- Bureau of Labor Statistics: Consumer Expenditures in 2024
- Bureau of Labor Statistics: Housing and Transportation Accounted for 50 Percent of Household Spending in 2024
- Federal Reserve Board: Economic Well Being of U.S. Households in 2025
- Federal Reserve Board: Press Release on the 2025 Household Well Being Report
- Harvard Joint Center for Housing Studies: Housing Unaffordability Soared to New Highs in 2024
- Consumer Financial Protection Bureau: Your Money, Your Goals Financial Empowerment Toolkit
- Bankrate: What Is the 50/30/20 Budget Rule?
- Kiplinger: The 50/30/20 Budget Rule, A Simple Way to Save Money
- Fox Business: What Is the 50/30/20 Budget Rule?
- Acorns: What Is the 50/30/20 Rule? A Simple Budget Method Explained
- SoFi: 50/30/20 Budget Rule, What It Is and Tips on Using It
- Citizens Bank: What Is the 50/30/20 Budget Rule?
- CollegeAve: The 50/30/20 Budget Rule

Daniel Arkwright
Daniel Arkwright is a Certified Business Coach and Advisor who helps founders build smarter plans and stronger businesses.


You May Also Like
How to Use AI at Work Without Sacrificing Quality: An Interview With an AI Workflow Specialist
How to Get a Small Business Loan: What Lenders Look For