-
The 50/30/20 Budget Rule Explained (With Examples)
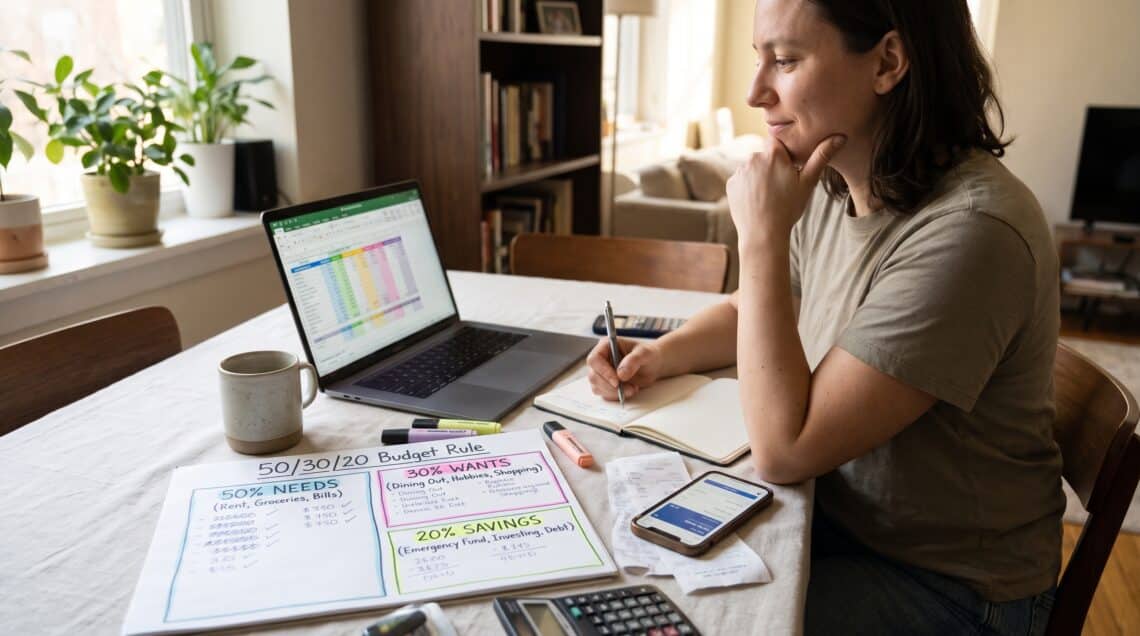
The 50/30/20 rule is usually the first budgeting framework I bring up with a new client. However, it’s rarely the one they end up following to the letter. That isn’t a knock on it. In fact, after years of sitting across the table from people with bank statements spread out and a shoebox of receipts nearby, I’ve come to see the rule as a diagnostic tool. In other words, it tells you, in about ten minutes, where your money is out of balance. What you do with that information, of course, is the actual work. In this guide, I’ll walk through what the rule says, where it came from, and…
-
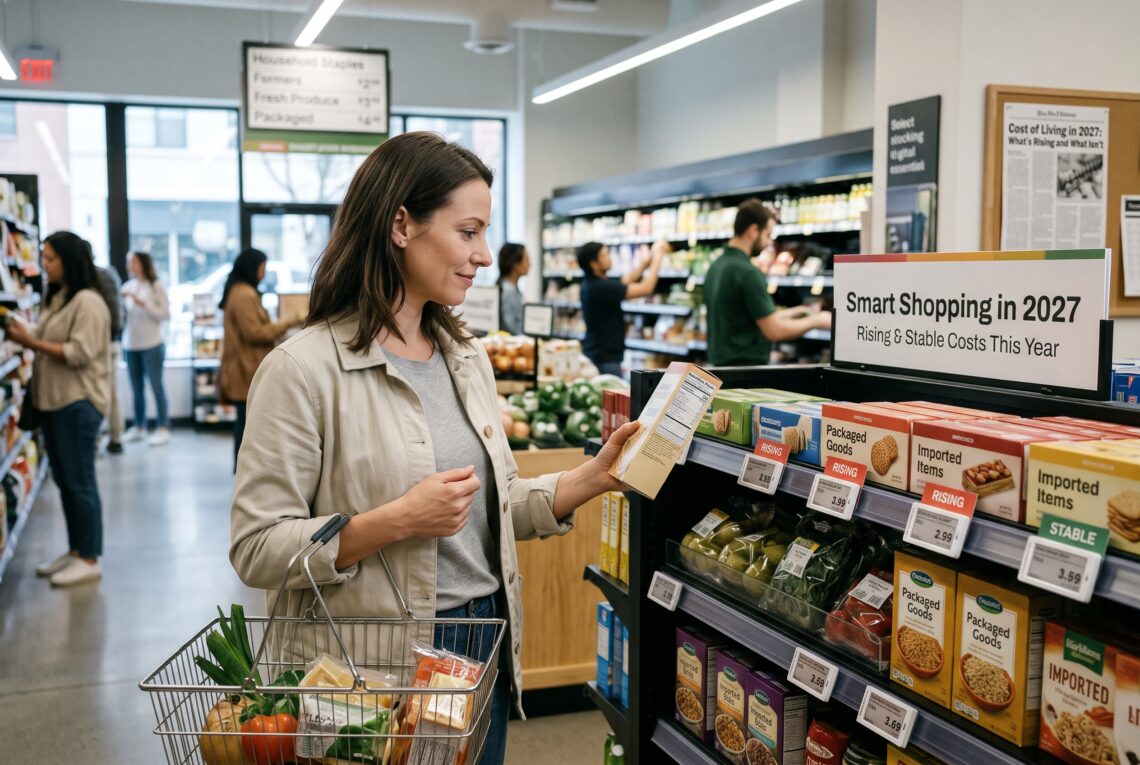
Cost of Living in 2027: What’s Rising and What Isn’t
Every autumn I rebuild the same spreadsheet to track cost of living trends for the year ahead. It is not fancy. It is a typical household budget split into about a dozen lines, rent or mortgage, groceries, electricity, gasoline, health coverage, insurance, eating out, and so on, and I run each line forward twelve months using the best official forecasts I can find. Most years the exercise is boring in a reassuring way. Everything drifts up by two or three percent and the story writes itself. This year it did not. When I ran the numbers for 2027, the lines pulled apart. Some costs that hurt badly in 2026 are…
-
How to Improve Your Credit Score: 7 Steps That Work
Most people who sit across from me in a counseling session open with the same sentence. “I just need to know how to improve my credit score.” They usually say it with a little embarrassment, like they’ve been caught doing something wrong. Then they slide a printout across the desk, or hold up their phone, and wait for me to tell them how bad it is. Here’s what I tell every one of them: a credit score is not a judgment of your character. It’s a math problem. And math problems have solutions. I’ve spent years as a certified credit counselor working with nurses, truck drivers, recent grads, retirees, and…
-
Debit Card vs Credit Card: When to Use Each
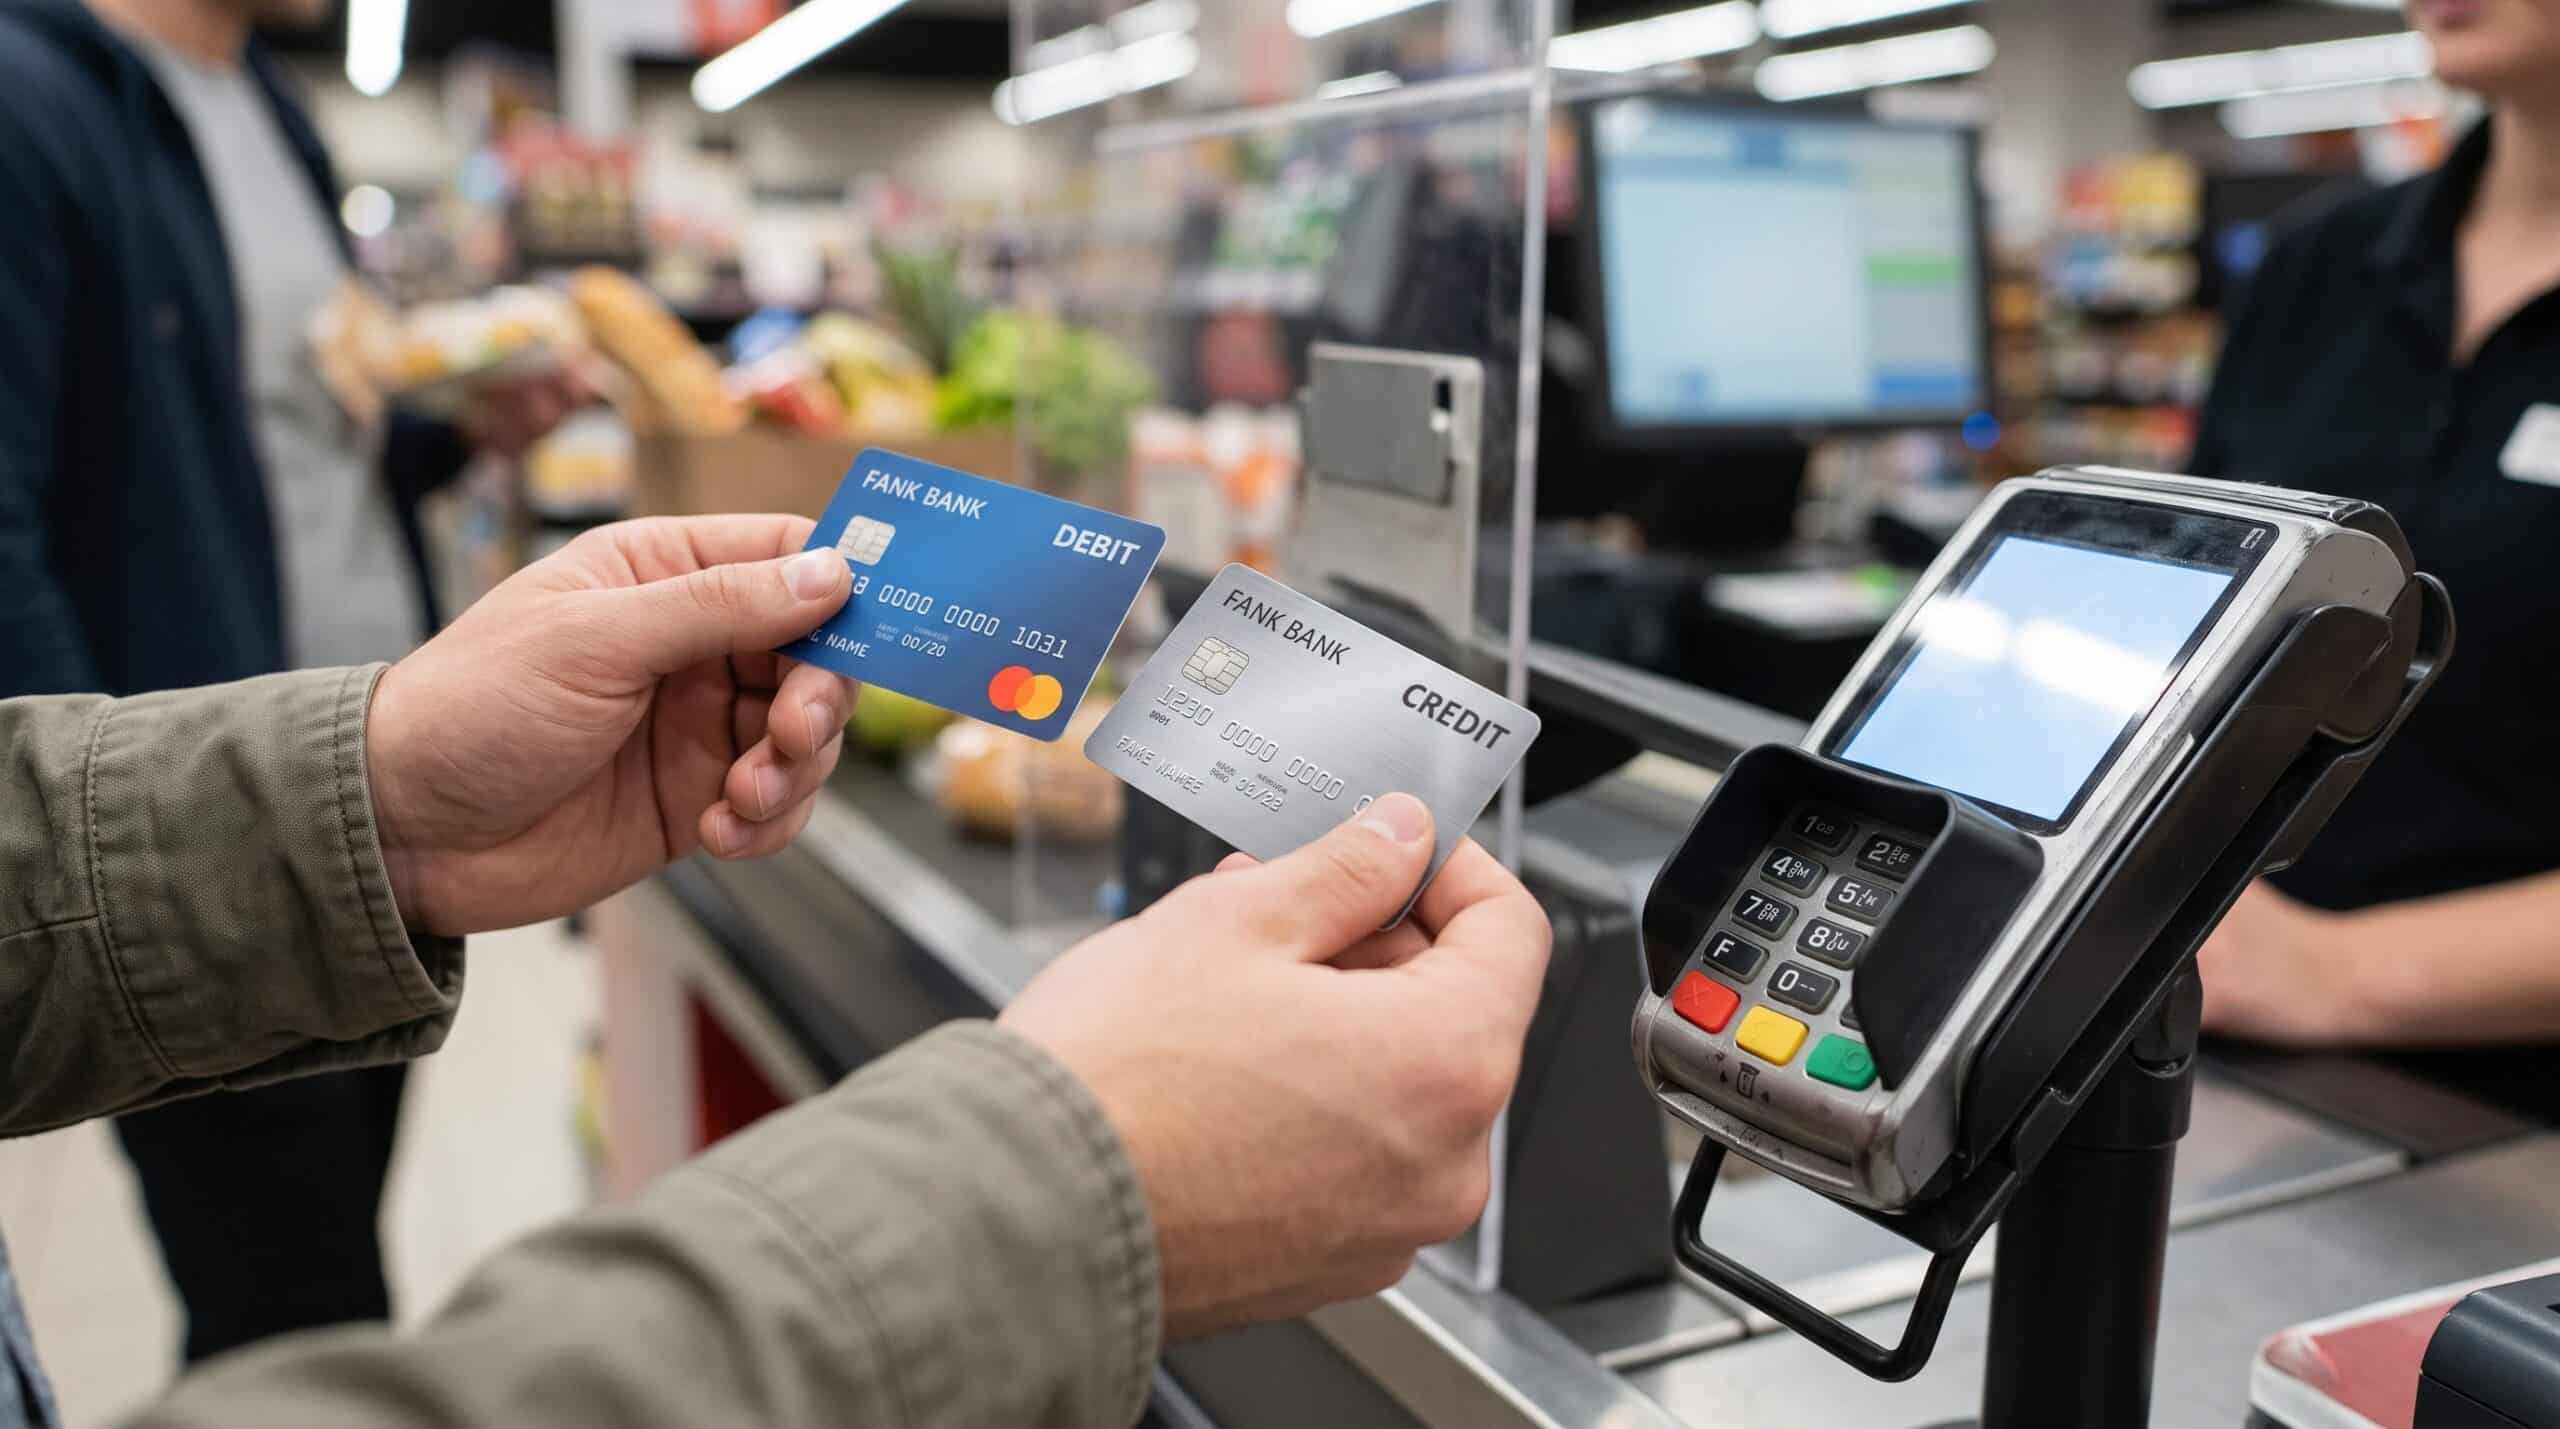
A woman I worked with a few years back, I’ll call her Marisol, came into our first session with her mind already made up on the debit card vs credit card question. Credit cards were something she simply did not trust. In her twenties she had run up a balance, spent most of her thirties paying it off, and when the last payment cleared she cut every card in half and promised herself she would live on debit for good. I respected that. It took real discipline. Then one Friday evening her debit card was skimmed at a gas pump. By Sunday, close to nine hundred dollars had left her…
-
15 Practical Ways to Save Money on Groceries
The grocery line is where I see budgets quietly fall apart, and it is also where I find the most reliable ways to save money on groceries without anyone at home feeling deprived. Rent is fixed. The car payment is fixed. But food? Food is the one category that moves every single week, and because it moves, most people never really know what they spend on it. I work as a financial coach and Accredited Financial Counselor (AFC®), and when a new client sits down with me, the grocery category is almost always the first place we find real money. Not because people are careless. It is because food spending…
-
How Much Emergency Fund Do I Need? A Financial Planner’s Guide to Finding Your Number
Almost every first meeting I have with a new client leads back to one simple question: “How much emergency fund do I need?” We usually start by going through retirement accounts, mortgages, and college plans, but everything eventually comes back to what happens if your income disappears tomorrow. I usually ask a direct question: “If your paycheck stopped tomorrow, how long could you keep the lights on without touching a credit card?” There is usually a pause. Sometimes a laugh. Occasionally someone says three months with confidence, but when we actually add up their checking and savings, the real answer turns out to be closer to five weeks. That gap…
-
How to Make a Budget You’ll Actually Stick To: A 10-Step Guide
I have sat across the table from a lot of people who were embarrassed about money, and most of them wanted to learn how to make a budget that would finally work. Some of them earned very little, while others earned a great deal. Still, almost all of them opened our first session with some version of the same sentence: “I’ve tried budgeting before, and it never works for me.” So here is what I tell every one of them. The budget did not fail because you are bad with money. Instead, it failed because it was built for someone else. In fact, it was built for a version of…